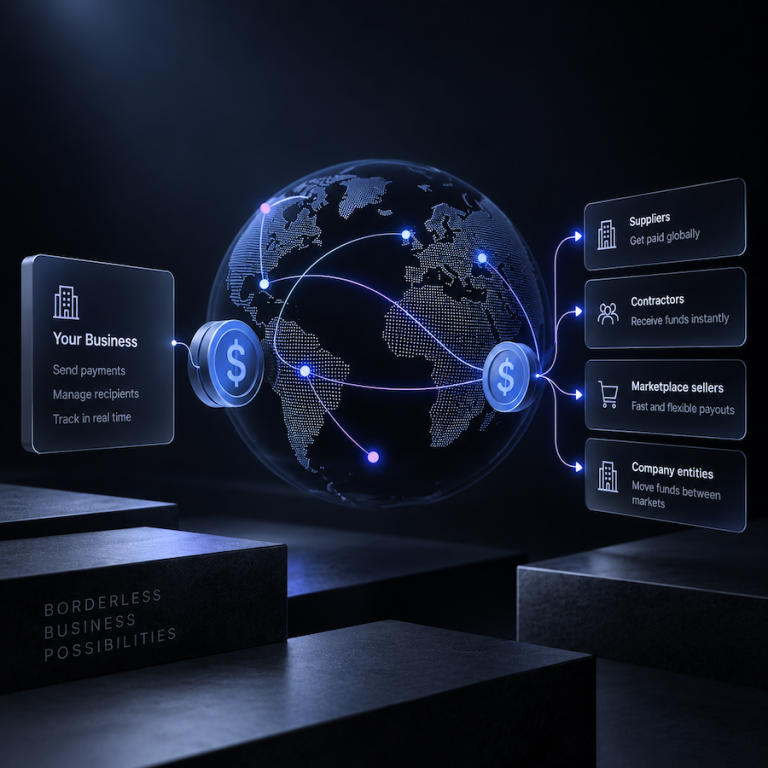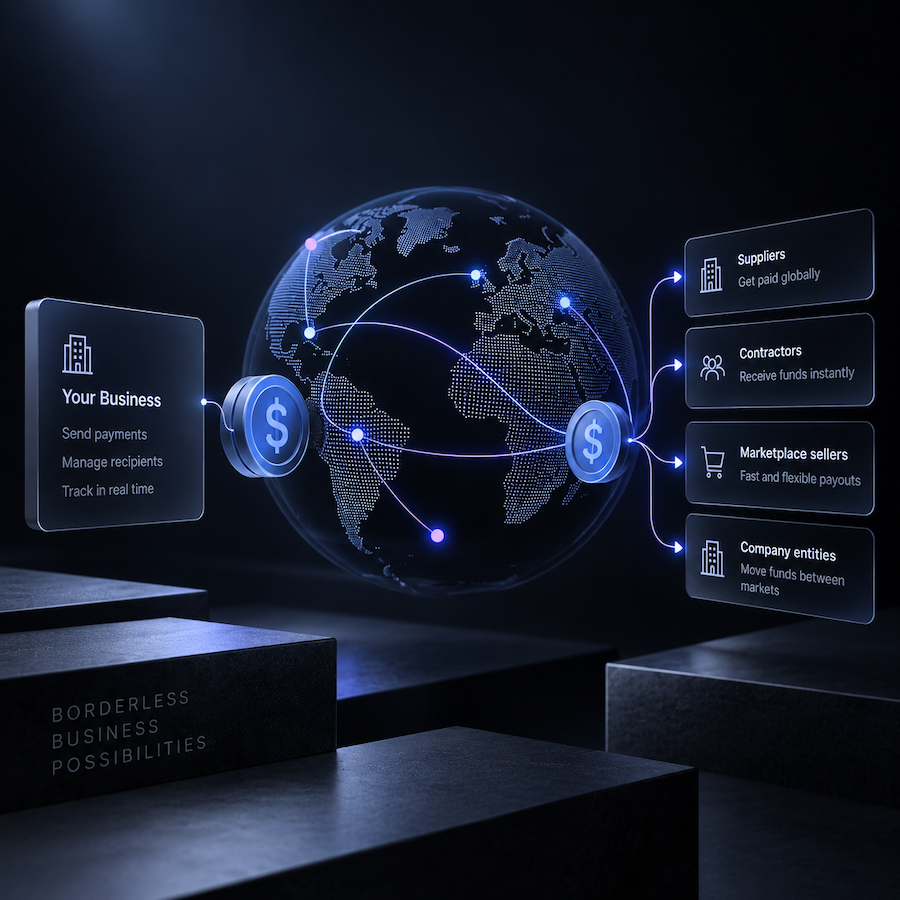

Businesses pay suppliers, contractors, marketplace sellers, and other company entities. Some of these payments stay within one country. Others move between currencies, banking systems, and regions.
Stablecoins can become part of these payment flows. A business can fund a payment with fiat currency, use a stablecoin for settlement, and let the recipient receive either a stablecoin or local currency. In another setup, both sides may already work with stablecoins and no fiat conversion is needed. The exact flow depends on how the business wants to send, receive, and manage money.
In this article, we will look at how B2B stablecoin payments work, where businesses use them, and what needs to be connected to integrate stablecoins into an existing payment workflow.
B2B stablecoin payments are transactions between businesses where a stablecoin is used to transfer or settle value.
The stablecoin does not have to be visible to both sides of the transaction.
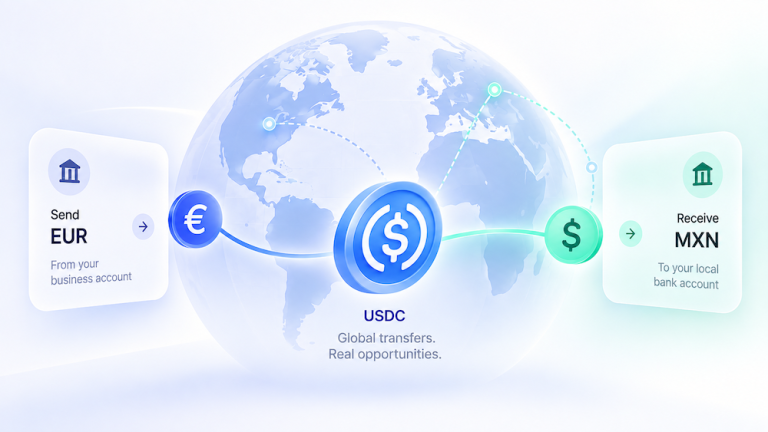
For example, a company can fund a supplier payment from its EUR business account. The payment system converts EUR into USDC and transfers it over a blockchain network. At the destination, USDC can be converted into the currency required by the supplier.
B2B business may fund the transaction from a bank account, payment account, wallet, or existing stablecoin balance. If the payment starts in fiat currency, an on-ramp or liquidity provider converts the required amount into a stablecoin. The stablecoin is then transferred over the selected blockchain network. What happens next depends on the recipient.
If the recipient accepts stablecoins, the payment can finish in a wallet or stablecoin account. If the recipient needs fiat currency, the stablecoin has to be converted and delivered through a local payment method.
For international payments, the complete flow may look like this: EUR → USDC → blockchain transfer → local currency
We explain this fiat-to-fiat process in more detail in our guide to stablecoin cross-border payments.
The blockchain transaction is only one step in the payment. Funding, conversion, compliance, payout, and reconciliation happen around it.
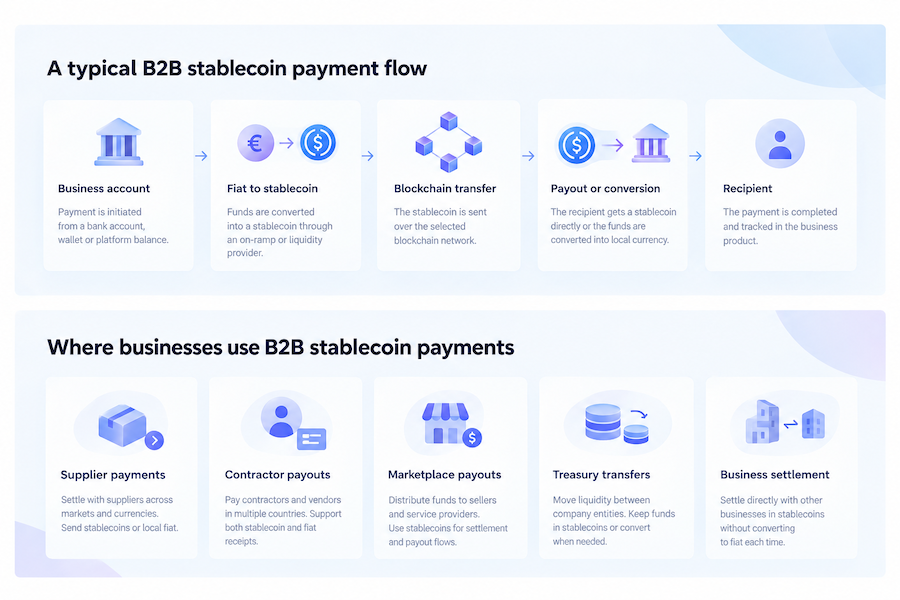
Stablecoins can support different business payment flows. The role of the stablecoin changes depending on where the money starts, who receives it, and whether either side wants to hold digital assets.
A company may work with suppliers in several countries while keeping its operating funds in one main currency.
Instead of managing a separate payment setup for every destination, the company can fund a supplier payment from its business account. The payment system converts the required amount into a stablecoin and uses it for settlement. At the destination, the supplier can receive the stablecoin directly or have it converted into local currency.
For example: EUR business account → USDC → supplier receives local currency
The stablecoin is useful here as the settlement asset between the funding and payout sides of the payment.
This model can also support suppliers that have different preferences. One supplier may want USDC in a wallet. Another may want fiat in a bank account. The business can initiate both payments from the same product while the infrastructure handles different routes in the background.
Companies may need to pay contractors, agencies, service providers, and other vendors across multiple countries.
These payments often involve many recipients rather than one large transfer.
A company could fund a payout batch in EUR or USD. The system calculates the amount for each recipient, converts funds into stablecoins where required, and sends the individual payments.
Recipients can then receive either stablecoins or local currency.
For example: Company funds $100,000 → payment batch → USDC settlement → 50 contractor payouts
At this point, the product needs more than the ability to send USDC. It needs recipient management, payout status, transaction tracking, approval rules, and reconciliation.
This becomes especially important when payouts happen every week or month.
A marketplace collects money from customers and later distributes funds to sellers or service providers.
Stablecoins can be used in the settlement and payout layer without changing the experience for the seller.
Imagine a marketplace operating in several markets. Sellers have balances inside the platform, but they want to withdraw those balances using different methods.
One seller may request USDC.
Another may request a payout to a local bank account.
The marketplace can use stablecoins to move value between its platform balance and payout providers, while the seller chooses how to receive the funds.
The flow could look like this: Marketplace balance → stablecoin settlement → local payout provider → seller bank account
This gives the marketplace one settlement layer that can connect to different payout destinations.
The marketplace still needs to manage seller balances, fees, payout status, failed withdrawals, and reconciliation between the platform ledger and external transactions.
A company operating through several legal entities may need to move liquidity between them.
For example, one entity may collect revenue while another needs funds for supplier payments, operating expenses, or local payouts.
If both entities can work with stablecoins, the transfer can happen directly: Company entity A → USDC → Company entity B
There may be no need to convert the stablecoin immediately after the transfer. The receiving entity can keep the balance and use it for another payment later.
This creates a different use case from a supplier payment. The stablecoin is not simply a temporary bridge between two fiat currencies. It can become part of the company’s treasury and liquidity infrastructure.
The product may therefore need wallet permissions, approval workflows, balance visibility across entities, transaction limits, and accounting records.
Some businesses already operate with digital assets and do not need fiat at either end of every transaction.
A company can invoice another business in a stablecoin and receive settlement directly into its wallet or account.
For example: Invoice in USDC → customer pays USDC → business receives USDC
The company can keep the funds in USDC, use them for another supplier payment, move them between treasury accounts, or convert them into fiat later.
This removes the need to perform a fiat conversion for every individual transaction.
It also changes what the payment product needs to manage. The business may need stablecoin balances, invoice matching, transaction history, wallet controls, and reconciliation between blockchain transactions and internal accounting records.
This is one of the main product decisions when adding stablecoin payments for businesses.
In the first model, the business continues working with fiat. It creates a payment in EUR or USD. The infrastructure converts the funds into a stablecoin, completes the blockchain leg, and converts the funds again when the recipient needs fiat.
Fiat → stablecoin → fiat
The business does not need to manage a stablecoin balance.
In the second model, the company holds stablecoins between transactions. It may receive USDC from customers, keep part of the balance in USDC, and use those funds later for supplier payments, treasury transfers, or payouts.
Receive USDC → hold balance → make another payment
Now the product needs to manage the balance itself.
Users need to see available funds and transaction history. The business may need rules for who can initiate or approve transfers. Wallet access and signing need to be controlled. Accounting systems need to know what happened to each transaction.
A third model can combine both approaches.
The business can hold a stablecoin balance but allow recipients to choose whether they receive USDC or fiat.
This gives the product more flexibility, but it also introduces more routes that have to be tracked and reconciled.
There is no single stablecoin integration that works for every B2B product. The architecture starts with the payment flow. Consider a platform where a European business funds payments in EUR and suppliers can choose between USDC and local fiat.
The product needs an interface where the business creates and manages payments.
Behind that interface, the EUR funding has to be detected and assigned to the correct account or transaction. If USDC is required, the funds need to be converted.
The product needs a wallet layer to manage blockchain addresses and transaction signing. It needs a blockchain integration to send and monitor the USDC transaction.
If the supplier chooses fiat, another conversion and a local payout are required.
Compliance checks may happen at different stages depending on the business model and providers involved.
The backend has to keep the complete transaction connected: Payment created → fiat received → USDC acquired → blockchain confirmed → conversion completed → recipient paid
These components form the stablecoin payment rails behind the product.
The user should not have to manage each component separately. For them, the workflow can remain: Choose recipient → Enter amount → Send → Track payment
ND Labs builds the product and integration layer around these components. Our stablecoin payment infrastructure development can include account and wallet functionality, transaction logic, blockchain integrations, fiat rails, compliance integrations, payout workflows, and backend systems.
B2B stablecoin payments are transactions between businesses where a stablecoin is used for payment or settlement. The stablecoin can move directly between business wallets or operate inside a payment flow between fiat funding and final payout.
Businesses can use stablecoins for supplier payments, contractor and vendor payouts, marketplace payouts, treasury transfers, and direct settlement with other businesses. The stablecoin may be sent directly to the recipient or converted into local currency before payout.
No. A business can fund a payment in fiat while the payment infrastructure handles the stablecoin conversion and blockchain transaction. Businesses that want to use stablecoins for treasury or repeated payments can also maintain a stablecoin balance.
Yes. A stablecoin can be used for the settlement part of the transaction and converted into local currency before the final payout. The supplier does not necessarily need a crypto wallet.
The integration depends on the complete payment flow. A product may need fiat rails, wallet infrastructure, blockchain integrations, liquidity, compliance services, payout providers, transaction monitoring, and reconciliation. The backend connects these components so the business can manage the payment as one transaction.
USDC and USDT are widely used options, but the stablecoin should be selected together with the network, markets, liquidity, fiat providers, payout routes, and compliance requirements of the product.
B2B stablecoin payments can look very different depending on how a business uses the stablecoin.
For one company, USDC may exist only between fiat funding and a supplier payout. Another may keep stablecoin balances and use them across supplier payments, treasury transfers, and settlements.
That difference determines what needs to be built around the transaction.
The payment flow comes first. Once the funding source, recipient, currencies, markets, payout method, and role of the stablecoin are clear, the infrastructure required to support that flow becomes much easier to define.